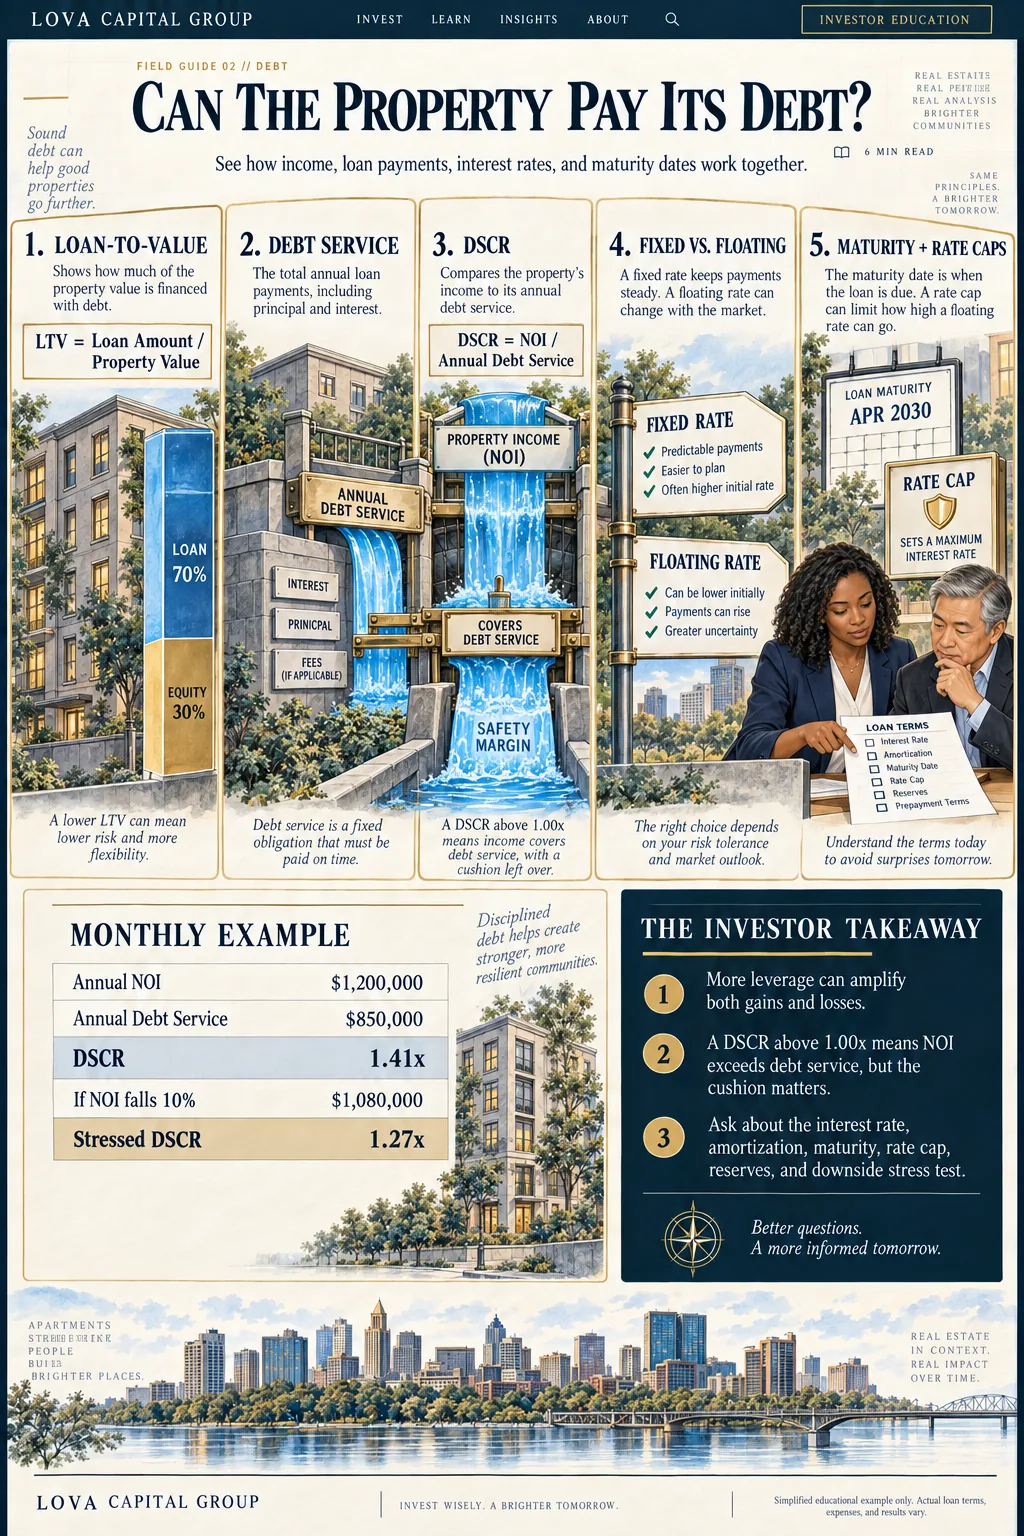
The Four Numbers to Know
Loan-to-Value, or LTV
LTV compares the loan balance with the property's stated value. A $6.8 million loan on a $10 million property has a 68% LTV. Lower leverage can create more room for value declines, but it does not remove risk.
Debt Service
Debt service is the required principal and interest payment. It may change over time depending on the loan's interest rate, amortization, and terms.
Debt Service Coverage Ratio, or DSCR
DSCR compares NOI with annual debt service. A ratio above 1.00x means current NOI exceeds scheduled debt service. It does not prove the investment is safe because NOI and borrowing costs can change.
Base Case and Stress Case
| Scenario | NOI | Debt Service | DSCR |
|---|---|---|---|
| Base case | $1,200,000 | $850,000 | 1.41x |
| NOI declines 10% | $1,080,000 | $850,000 | 1.27x |
This simplified stress test holds debt service constant. If the loan has a floating rate, required payments could rise while NOI falls, producing a more severe result.
Fixed, Floating, and Maturity Risk
- Fixed-rate debt: the stated rate generally remains constant for a defined period.
- Floating-rate debt: the rate changes with an index plus a lender spread.
- Rate cap: a contract designed to limit the applicable benchmark rate for a stated period and not a guarantee against all financing risk.
- Maturity: the date the loan must be repaid or refinanced. Refinancing may be unavailable or more expensive.
Questions to Ask
- Is the loan fixed or floating, and what determines the rate?
- What are the amortization schedule, maturity date, extension options, and fees?
- Is there a rate cap, when does it expire, and what could replacement cost?
- What DSCR or other lender covenants apply?
- How does the deal perform if NOI falls or refinancing proceeds are lower than expected?
What to Remember
- Leverage can amplify both gains and losses.
- A DSCR above 1.00x is not automatically comfortable.
- The interest rate, amortization, maturity, extensions, caps, covenants, and reserves all matter.
- Downside testing should examine changes in both NOI and borrowing cost.
Knowledge Check
Does lower LTV eliminate investment risk?
No. It may reduce leverage risk, but property operations, market value, financing, and execution risks remain.
Why stress both NOI and interest expense?
Because a floating-rate property can experience weaker income and higher debt payments at the same time.
What happens at loan maturity?
The balance generally must be repaid, sold, extended, or refinanced, and none of those outcomes is guaranteed.
This lesson is for general educational and informational purposes only. It is not investment, legal, tax, accounting, retirement-plan, or financial advice and is not an offer to sell or a solicitation to purchase any security. Examples are simplified and hypothetical. Private real estate investments are speculative, illiquid, and involve substantial risk, including possible loss of principal. Rules and individual circumstances vary. Review definitive offering documents and consult your own qualified advisers.