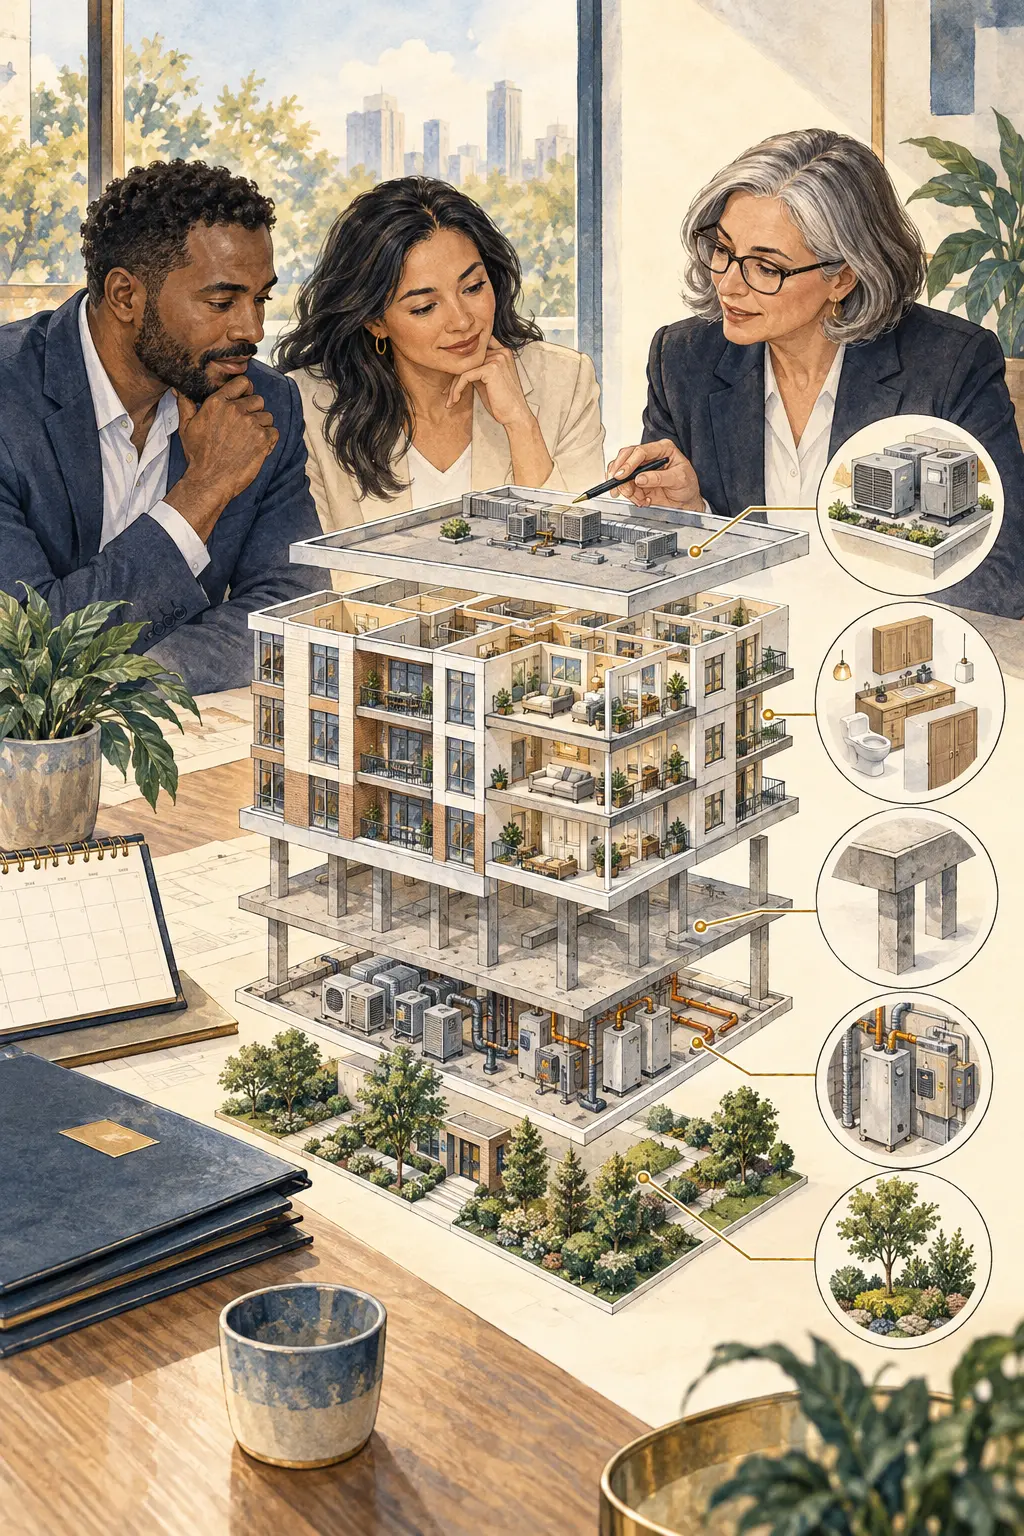
Depreciation Is a Tax Allocation
For tax purposes, eligible building cost is generally recovered over specified periods. Land is not depreciable. Depreciation is a noncash deduction, but it does not mean the property avoided real capital costs. The partnership generally reports each investor's allocated items on a Schedule K-1.
Taxable income and cash distributions can differ. An investor can receive cash with little current taxable income, or be allocated taxable income without matching cash, depending on operations, financing, reserves, and the governing documents.
Cost Segregation Changes Timing
A cost-segregation study identifies qualifying building components that may be recovered over shorter tax lives than the main building. That can accelerate deductions. It usually changes when deductions are taken, not the total economic cost of the property.
Bonus-depreciation rules and percentages can change. Study quality, placed-in-service dates, elections, ownership period, and current law all matter. Website examples should never promise a specific deduction.
Passive Activity and Basis Can Limit Use
Rental real estate activity is often passive for a passive investor. Passive losses may generally offset passive income, subject to detailed exceptions and limitations. Basis, at-risk rules, investor status, other activities, and elections can affect whether a deduction is currently usable or carried forward.
The Exit Can Reverse Part of the Timing Benefit
A sale can create gain and depreciation recapture. State filing requirements may apply in multiple jurisdictions. Tax-exempt retirement accounts can face unrelated business income or debt-financed income issues. A 1031 exchange by the entity is not the same as an individual investor choosing to exchange an interest.
Tax outcomes are personal. A qualified tax adviser should review the actual documents, ownership structure, financing, and investor circumstances.
What to Remember
- Depreciation is a tax concept, not a cash distribution.
- Cost segregation may accelerate deductions but does not create a guaranteed benefit.
- Passive-loss, basis, at-risk, state, and retirement-account rules can limit or change outcomes.
- A later sale can involve gain and depreciation recapture.
Questions to Ask
Will a cost-segregation study be performed?
Ask who prepares it, when it is expected, and how estimates will be communicated without promising personal tax results.
Could taxable income exceed cash distributed?
Review distribution discretion, tax-allocation provisions, reserves, and tax-distribution language.
What happens at sale?
Ask a tax adviser about basis, suspended losses, depreciation recapture, state filings, and investor-specific consequences.
This lesson is for general educational and informational purposes only. It is not investment, legal, tax, accounting, retirement-plan, or financial advice and is not an offer to sell or a solicitation to purchase any security. Examples are simplified and hypothetical. Private real estate investments are speculative, illiquid, and involve substantial risk, including possible loss of principal. Rules and individual circumstances vary. Review definitive offering documents and consult your own qualified advisers.