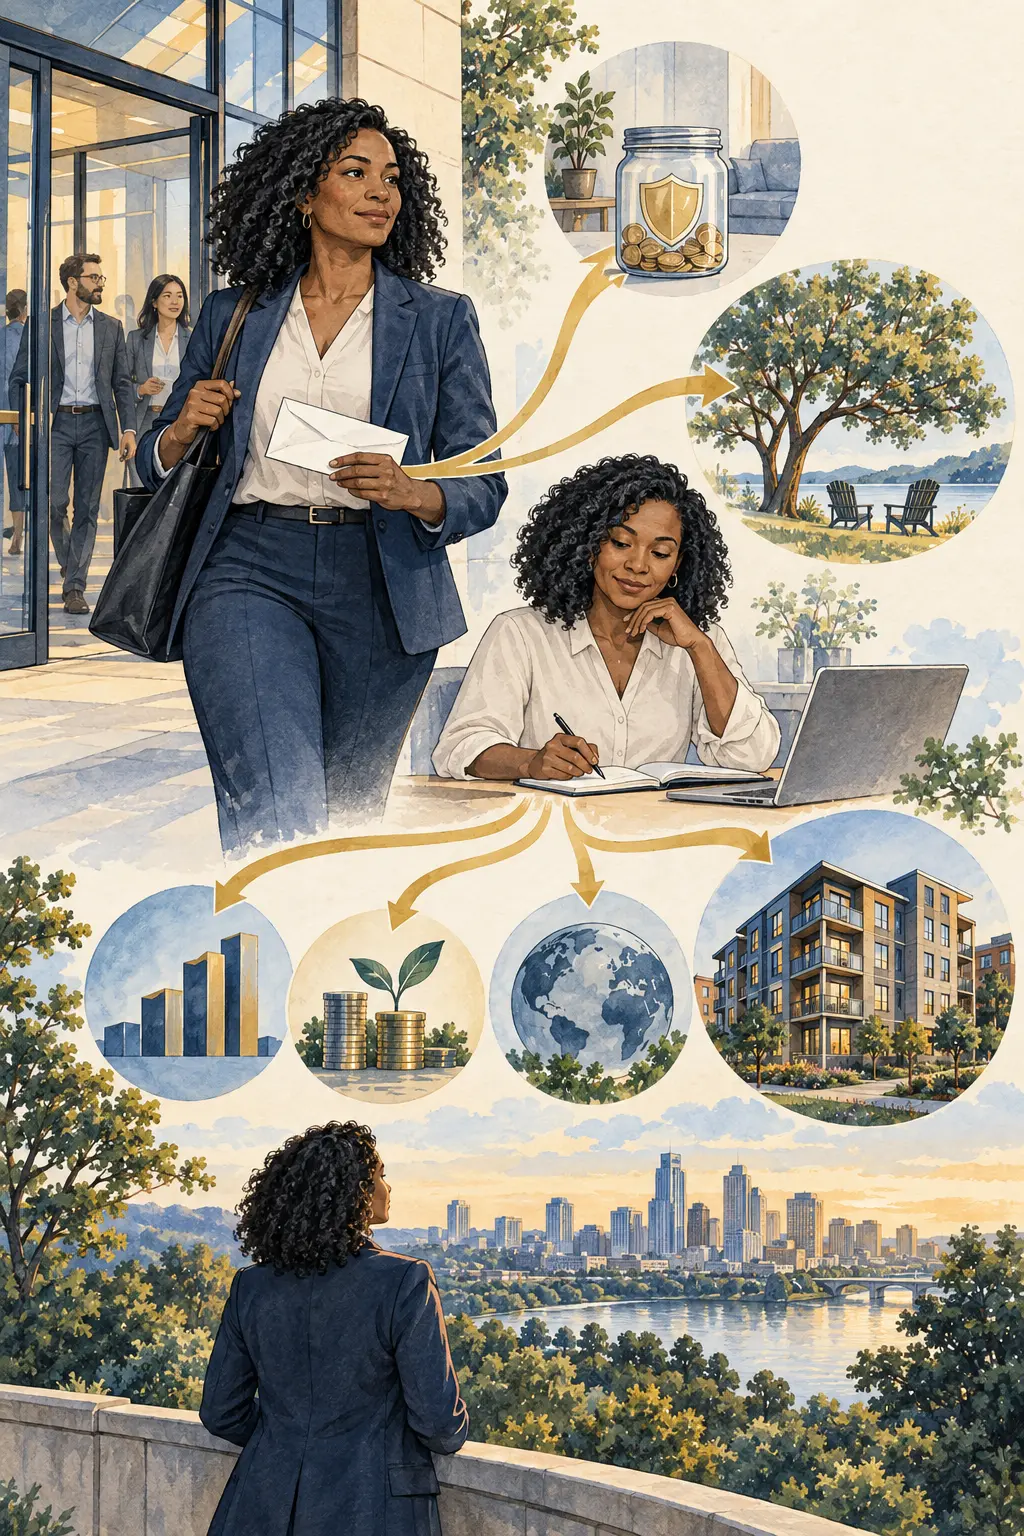
Build the Capital Stack at Home First
Before evaluating a private real estate opportunity, define what your household cannot afford to lock up. Consider an emergency reserve, expected taxes, high-interest debt, near-term purchases, tuition, caregiving, job-transition risk, and planned retirement contributions. Money allocated to a private offering may be unavailable for years.
Employer matching contributions can be economically significant, but benefit-plan choices and tax questions belong with qualified advisers. The point is sequencing, not a universal rule.
Separate Capacity From Desire
Investment capacity is the amount you could lose or leave illiquid without disrupting obligations. Investment desire is how attractive the opportunity appears. Excitement should not expand capacity.
Map the Risks You Already Own
A corporate professional may already depend on one company or industry for salary, bonus, health benefits, retirement contributions, RSUs, options, and career opportunity. Adding an investment exposed to the same local economy or business cycle may increase concentration even if the asset class is different.
Also map existing real estate through a primary residence, rental property, REITs, or funds. Diversification does not guarantee against loss, but seeing the whole balance sheet helps prevent accidental concentration.
Use a Staged Learning Process
Start by studying structures and documents, then review several opportunities without assuming you must invest. Compare sponsors, leverage, market assumptions, fees, waterfalls, and reporting. A passed opportunity can still be valuable education.
When an opportunity arrives, slow down enough to read the definitive documents and obtain independent advice. A deadline does not make an investment suitable.
What to Remember
- Protect liquidity before allocating capital to a long-term private investment.
- Capacity to invest is different from enthusiasm for a deal.
- Include career, employer stock, home, and existing real estate in concentration analysis.
- Education and comparison can happen without an obligation to invest.
Questions to Ask
What if distributions stop for two years?
Test whether household plans remain intact without projected cash flow.
What if my job changes?
Consider severance, vesting, benefit changes, geographic moves, and the value of accessible cash.
What role would this investment play?
Define whether the goal is current income, long-term growth, diversification, or education, then test whether the terms support that goal.
This lesson is for general educational and informational purposes only. It is not investment, legal, tax, accounting, retirement-plan, or financial advice and is not an offer to sell or a solicitation to purchase any security. Examples are simplified and hypothetical. Private real estate investments are speculative, illiquid, and involve substantial risk, including possible loss of principal. Rules and individual circumstances vary. Review definitive offering documents and consult your own qualified advisers.